
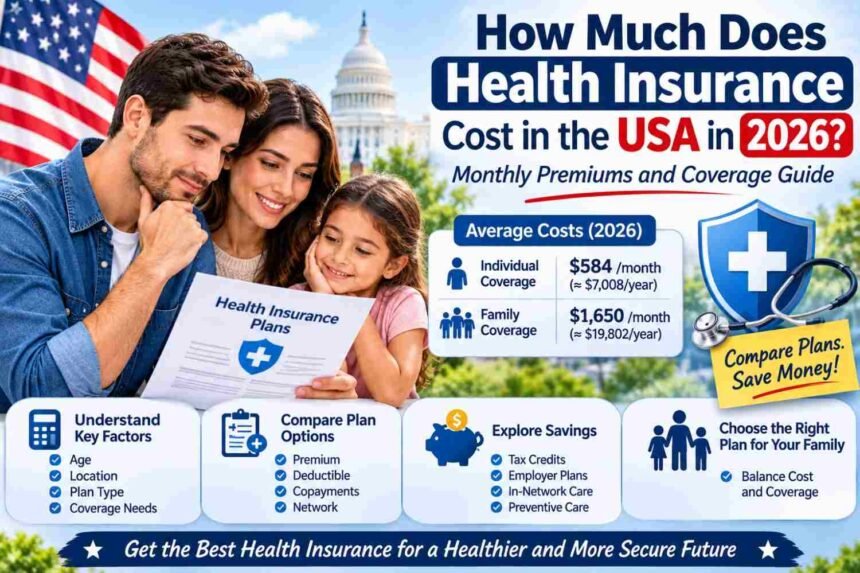
Health insurance is one of the biggest expenses many American households need to consider when planning their monthly budgets. Whether you are purchasing an individual policy, covering your entire family, or receiving insurance through your employer, understanding the actual cost of healthcare coverage is essential.
- How Much Does Health Insurance Cost in the USA?
- Average Health Insurance Costs by Coverage Type
- 1. Employer-Sponsored Health Insurance
- 2. Individual Health Insurance
- 3. Family Health Insurance
- 4. Medicare
- 5. Medicaid
- What Factors Affect Health Insurance Costs in 2026?
- Bronze vs. Silver vs. Gold Health Insurance Costs
- How to Calculate Your Total Annual Health Insurance Cost
- Seven Ways to Save Money on Health Insurance
- 1. Compare Multiple Insurance Providers
- 2. Check Your Eligibility for Marketplace Subsidies
- 3. Explore Medicaid and CHIP
- 4. Consider an HSA-Eligible Health Plan
- 5. Use In-Network Healthcare Providers
- 6. Review Prescription Drug Coverage
- 7. Review Your Coverage Every Year
- Is Health Insurance Cheaper Through an Employer or the Marketplace?
- When Is the Best Time to Buy Health Insurance?
- Frequently Asked Questions About Health Insurance Costs
- How much does health insurance cost per month in the USA?
- What is the cheapest health insurance option in the USA?
- Is health insurance free in the USA?
- Can I get health insurance without a job?
- Does health insurance cost more for older adults?
- Is a high-deductible health insurance plan worth it?
- Can I change my health insurance plan during the year?
- Final Thoughts
In 2026, health insurance costs vary significantly depending on your age, location, household size, coverage type, and eligibility for financial assistance.
Some Americans receive health insurance through their employers, while others purchase individual policies through the Affordable Care Act (ACA) Marketplace. Eligible individuals and families may also qualify for government assistance through programs such as Medicaid and premium tax credits.
However, the monthly premium is only one part of the total cost. Deductibles, copayments, coinsurance, prescription expenses, and out-of-pocket maximums can all affect how much you spend on healthcare throughout the year.
So, how much does health insurance actually cost in the United States in 2026?
Let’s explore average insurance expenses, different coverage options, factors affecting premiums, and practical ways to find affordable health insurance.
How Much Does Health Insurance Cost in the USA?
There is no single health insurance price that applies to every American. Costs depend on the type of coverage, the insurer, the location, and the financial assistance available to the applicant.
Employer-sponsored health insurance, individual Marketplace coverage, and government-supported programs all have different pricing structures.
According to KFF’s 2026 Employer Health Benefits Survey:
- Average annual premium for employer-sponsored individual coverage: $9,804.
- Average annual premium for employer-sponsored family coverage: $28,303.
- Average annual premium contribution from workers toward family coverage: $7,471.
These figures represent total employer-sponsored premiums and employee contributions, not necessarily the amount an individual employee pays directly. Employers generally cover part of the premium.
For individual Marketplace coverage, costs can be substantially different. Eligible consumers may qualify for premium tax credits that reduce their monthly payments.
The actual price you receive depends on your circumstances and the plans available in your area.
Average Health Insurance Costs by Coverage Type
Understanding the different coverage options can help you estimate what you might pay.
1. Employer-Sponsored Health Insurance
Many Americans receive health insurance through their workplace.
Under employer-sponsored coverage, the company typically pays part of the insurance premium, while employees contribute the remaining amount through payroll deductions.
This arrangement can make coverage more affordable than purchasing an individual policy without employer assistance.
The cost depends on several factors:
- Whether you choose individual or family coverage.
- The employer’s contribution.
- The selected insurance plan.
- The deductible and out-of-pocket maximum.
- The healthcare provider network.
Before enrolling, compare the available plans and check whether your preferred doctors, hospitals, and prescription medications are covered.
2. Individual Health Insurance
Individual health insurance is designed for people who purchase coverage independently rather than receiving it through an employer.
This option may be suitable for:
- Self-employed individuals.
- Freelancers and independent contractors.
- People working for companies without health benefits.
- Individuals between jobs.
- Early retirees who are not yet eligible for Medicare.
You can compare qualifying individual plans through the federal Health Insurance Marketplace or a state-based Marketplace.
Depending on your household income and eligibility, you may qualify for financial assistance that reduces the monthly premium.
3. Family Health Insurance
Family health insurance covers multiple household members under one policy.
Instead of purchasing separate individual plans for each person, families can compare plans that provide coverage for spouses and eligible dependents.
The total premium depends on the covered household members, location, plan type, and applicable rating rules.
When comparing family coverage, pay attention to:
- Monthly family premiums.
- Individual deductibles.
- Family deductibles.
- Individual out-of-pocket maximums.
- Family out-of-pocket maximums.
- Pediatric and preventive care benefits.
- Prescription drug coverage.
A plan with a higher monthly premium may offer better financial protection if several family members regularly need medical care.
4. Medicare
Medicare is a federal health insurance program primarily designed for people aged 65 and older.
Certain younger individuals with qualifying disabilities or specific medical conditions may also qualify.
Medicare costs depend on the type of coverage selected.
Original Medicare generally includes:
- Part A: Hospital insurance.
- Part B: Medical insurance.
Beneficiaries may also consider Part D prescription drug coverage, Medicare Advantage plans, and Medicare Supplement Insurance.
Each option has different premiums, deductibles, provider networks, and coverage requirements.
People approaching Medicare eligibility should review the available options and enrollment deadlines carefully.
5. Medicaid
Medicaid provides health coverage to eligible individuals and families based on federal and state requirements.
Eligibility depends on factors such as household income, family size, age, disability status, and state-specific rules.
For eligible beneficiaries, Medicaid may provide coverage with little or no monthly premium.
Because eligibility requirements differ between states, applicants should check their state’s official Medicaid program.
What Factors Affect Health Insurance Costs in 2026?
Insurance companies and government programs use different rules to determine health insurance costs.
Understanding the main factors can help you estimate your potential expenses.
Age
Age can influence premiums for many individual and family Marketplace plans.
Older adults may pay higher premiums than younger adults, subject to applicable federal and state rating rules.
However, Medicare eligibility can change the available coverage options for people aged 65 and older.
Location
Where you live can have a significant impact on health insurance prices.
Premiums can differ between states, counties, and ZIP codes because of:
- Local healthcare costs.
- Insurance company competition.
- Provider availability.
- Regional medical spending.
- State insurance regulations.
- The number of available plans.
For example, the cost of a comparable Marketplace plan may be substantially different in New York, Florida, Texas, or California.
This is why comparing plans using your actual ZIP code is important.
Household Size
Household size can affect eligibility for financial assistance and the cost of family coverage.
When applying for Marketplace insurance, household income and family circumstances are important considerations.
Make sure your application includes accurate household information.
Type of Health Insurance Plan
Different insurance plans have different pricing structures.
Bronze plans generally have lower premiums and higher cost-sharing, while Gold and Platinum plans generally have higher premiums and lower cost-sharing.
Silver plans occupy the middle of the metal-tier structure and are particularly important for people who qualify for cost-sharing reductions.
Tobacco Use
In many states, Marketplace insurers may charge higher premiums to tobacco users, subject to federal and state restrictions.
Some states prohibit or restrict tobacco-related premium adjustments.
Check the applicable rules in your state.
Financial Assistance
Eligible Marketplace consumers may qualify for premium tax credits.
These credits can reduce the amount paid each month for qualifying health insurance coverage.
Some consumers may also qualify for cost-sharing reductions, which can lower deductibles, copayments, coinsurance, and out-of-pocket maximums.
Eligibility depends on income, household size, access to other coverage, and applicable federal rules.
Bronze vs. Silver vs. Gold Health Insurance Costs
Marketplace health insurance plans are organized into four main metal categories: Bronze, Silver, Gold, and Platinum.
These categories describe how healthcare costs are generally shared between the insurer and the policyholder.
They do not represent the quality of doctors or medical treatment.
Bronze Plans
Bronze plans generally offer lower monthly premiums and higher deductibles.
They may be attractive to individuals who want to keep monthly insurance expenses manageable and can afford higher out-of-pocket costs when receiving treatment.
However, unexpected medical expenses can be substantial.
Silver Plans
Silver plans provide a middle-ground cost-sharing structure.
They are particularly important because eligible consumers may qualify for cost-sharing reductions when enrolling in a qualifying Silver plan through the Marketplace.
For people who qualify, these reductions can significantly lower healthcare expenses.
Gold Plans
Gold plans generally have higher monthly premiums than Bronze and Silver plans but lower cost-sharing when covered medical services are used.
They may be worth considering for people who expect regular medical appointments, prescription expenses, or specialist treatment.
Platinum Plans
Platinum plans generally have the highest premiums among the four metal categories and lower cost-sharing.
However, availability varies by location, and they may not be offered in every Marketplace area.
Which Metal Tier Should You Choose?
The right option depends on your healthcare needs and financial situation.
If you rarely visit doctors and want lower monthly payments, a Bronze plan may be worth considering.
If you qualify for cost-sharing reductions, a Silver plan may provide particularly valuable benefits.
If you expect frequent medical treatment, compare Gold and other plans with lower deductibles and out-of-pocket costs.
Do not select a plan based solely on its metal category. Review its actual benefits and expenses.
How to Calculate Your Total Annual Health Insurance Cost
One common mistake when comparing health insurance plans is looking only at the monthly premium.
Your actual annual healthcare expenses can be considerably higher.
To estimate your total costs, consider:
- Annual insurance premiums.
- Expected medical expenses.
- Deductibles.
- Copayments.
- Coinsurance.
- Prescription medication costs.
- Potential out-of-network expenses.
Consider this hypothetical example.
Plan A: Lower Monthly Premium
- Monthly premium: $250.
- Annual premium: $3,000.
- Deductible: $5,000.
- Coinsurance: 30%.
Plan B: Higher Monthly Premium
- Monthly premium: $400.
- Annual premium: $4,800.
- Deductible: $2,000.
- Coinsurance: 20%.
Plan A costs less each month, but it requires a higher deductible and coinsurance.
Plan B costs more annually in premiums but may provide better financial protection when medical treatment is necessary.
If you expect substantial medical expenses, Plan B could offer better overall value.
These figures are illustrative examples, not actual insurance quotes.
Your final decision should also consider provider networks, covered services, prescription benefits, and the out-of-pocket maximum.
Seven Ways to Save Money on Health Insurance
Finding affordable health insurance does not necessarily mean choosing the cheapest available policy.
Here are seven practical ways to manage healthcare expenses.
1. Compare Multiple Insurance Providers
Different insurers may offer different premiums and coverage options for similar benefits.
Compare several plans before enrolling.
Look at:
- Monthly premiums.
- Deductibles.
- Coinsurance.
- Copayments.
- Out-of-pocket maximums.
- Provider networks.
- Prescription coverage.
Make sure you are comparing similar coverage levels.
2. Check Your Eligibility for Marketplace Subsidies
Eligible consumers may receive premium tax credits that reduce their monthly insurance payments.
The amount of assistance depends on household income, household size, location, and applicable rules.
Do not assume that you must pay the full listed premium.
Complete an application through the official Marketplace to determine your eligibility.
3. Explore Medicaid and CHIP
If your household income is limited, Medicaid or the Children’s Health Insurance Program may provide affordable coverage.
Eligibility varies by state and household circumstances.
Families should check these options before purchasing a private policy.
4. Consider an HSA-Eligible Health Plan
A qualifying High-Deductible Health Plan may allow you to contribute to a Health Savings Account.
An HSA provides tax advantages when used according to applicable rules for qualified medical expenses.
However, consider the deductible and total potential medical expenses before selecting a high-deductible plan.
5. Use In-Network Healthcare Providers
Insurance companies negotiate rates with participating healthcare providers.
Receiving covered services from in-network doctors and hospitals can help reduce your expenses.
Always confirm that your provider participates in your specific plan.
6. Review Prescription Drug Coverage
Prescription medications can add significantly to annual healthcare expenses.
Check whether your regular medications are included in the plan’s formulary.
Compare generic and brand-name medication coverage, pharmacy networks, and applicable copayments.
7. Review Your Coverage Every Year
Your healthcare needs and financial circumstances can change.
Review your policy during the applicable enrollment period.
Compare your existing coverage with other available plans and check whether you qualify for new discounts or financial assistance.
Is Health Insurance Cheaper Through an Employer or the Marketplace?
Employer-sponsored coverage and Marketplace insurance have different advantages.
Employer-sponsored insurance can be attractive because employers generally contribute toward the premium.
However, some individuals may find Marketplace coverage more suitable, particularly if they qualify for financial assistance.
Consider the following differences:
| Feature | Employer Insurance | Marketplace Insurance |
|---|---|---|
| Premium contribution | Often shared with employer | Paid by consumer, potentially reduced by tax credits |
| Plan selection | Limited to employer offerings | Depends on local Marketplace options |
| Financial assistance | Employer contributions | Eligible consumers may qualify for tax credits |
| Enrollment | Employer enrollment periods | Annual Open Enrollment and qualifying exceptions |
| Provider networks | Depend on employer plan | Depend on selected Marketplace plan |
One important consideration is that access to affordable employer-sponsored coverage can affect eligibility for Marketplace premium tax credits.
Compare the actual costs before deciding.
When Is the Best Time to Buy Health Insurance?
For most individual Marketplace coverage, enrollment follows an annual Open Enrollment Period.
Outside that period, you may qualify for a Special Enrollment Period after certain qualifying life events.
Examples can include:
- Losing qualifying health insurance.
- Getting married.
- Having a baby.
- Adopting a child.
- Moving and meeting applicable eligibility requirements.
Employer-sponsored plans have their own enrollment periods and qualifying life event rules.
Medicaid and CHIP applications are generally accepted throughout the year for eligible applicants.
If you need coverage, do not wait until the last minute to review your options.
Check official enrollment dates and eligibility requirements before applying.
Frequently Asked Questions About Health Insurance Costs
How much does health insurance cost per month in the USA?
There is no universal monthly price. Costs depend on age, location, coverage type, household size, and eligibility for financial assistance.
Employer-sponsored coverage may involve contributions from both the employer and employee, while Marketplace plans may qualify for premium tax credits.
What is the cheapest health insurance option in the USA?
The most affordable option depends on your circumstances.
Eligible individuals may qualify for Medicaid, CHIP, employer-sponsored coverage, or subsidized Marketplace insurance.
Compare the available options rather than assuming that the lowest-premium private plan will be the cheapest overall.
Is health insurance free in the USA?
Some eligible individuals may receive Medicaid coverage with little or no premium.
Certain Marketplace consumers may also qualify for plans with very low monthly premiums after financial assistance.
However, coverage rules, deductibles, copayments, and other expenses vary.
Can I get health insurance without a job?
Yes. People without employment may qualify for Marketplace coverage, Medicaid, or other available insurance options.
Eligibility depends on income, household circumstances, and applicable rules.
Does health insurance cost more for older adults?
Marketplace premiums can increase with age, subject to applicable rating rules.
However, people aged 65 and older may qualify for Medicare, which has a different cost structure.
Is a high-deductible health insurance plan worth it?
A high-deductible plan may be appropriate for someone who wants lower monthly premiums and can afford higher initial medical expenses.
However, it may not be suitable for individuals who expect frequent treatment or cannot comfortably manage a large deductible.
Can I change my health insurance plan during the year?
Generally, Marketplace plan changes are limited to Open Enrollment and qualifying Special Enrollment Periods.
Employer-sponsored plans and Medicare have separate enrollment rules.
Some government programs, including Medicaid and CHIP, accept applications throughout the year.
Final Thoughts
Health insurance costs in the United States depend on several factors, and the most affordable option is not necessarily the one with the lowest monthly premium.
In 2026, consumers should pay particular attention to premiums, deductibles, provider networks, prescription drug coverage, and eligibility for financial assistance.
If you receive insurance through your employer, compare the available benefits and employee contributions. If you purchase coverage independently, investigate Marketplace plans and government assistance programs.
Families should also evaluate their total annual healthcare expenses rather than focusing only on individual premiums.
Before enrolling, review the policy documents and confirm that your preferred doctors, hospitals, and medications are covered.
The best health insurance plan is one that fits your household budget while providing meaningful financial protection when you need medical care.